

Many active invetors hold cash, some up to 10% of the portfolio. When asked why, the standard answer is optionality: the cash is there to buy equities after the market falls. The answer is usually accepted and the conversation moves on.
An option has a price, and this one does too. The price is cash drag: the return given up by holding T-bills instead of equities on 10% of the portfolio. The payoff is the ability to buy equities after a fall. I tested whether the payoff has covered the price, using S&P 500 data from 1934 to 2026.
Summary of results:
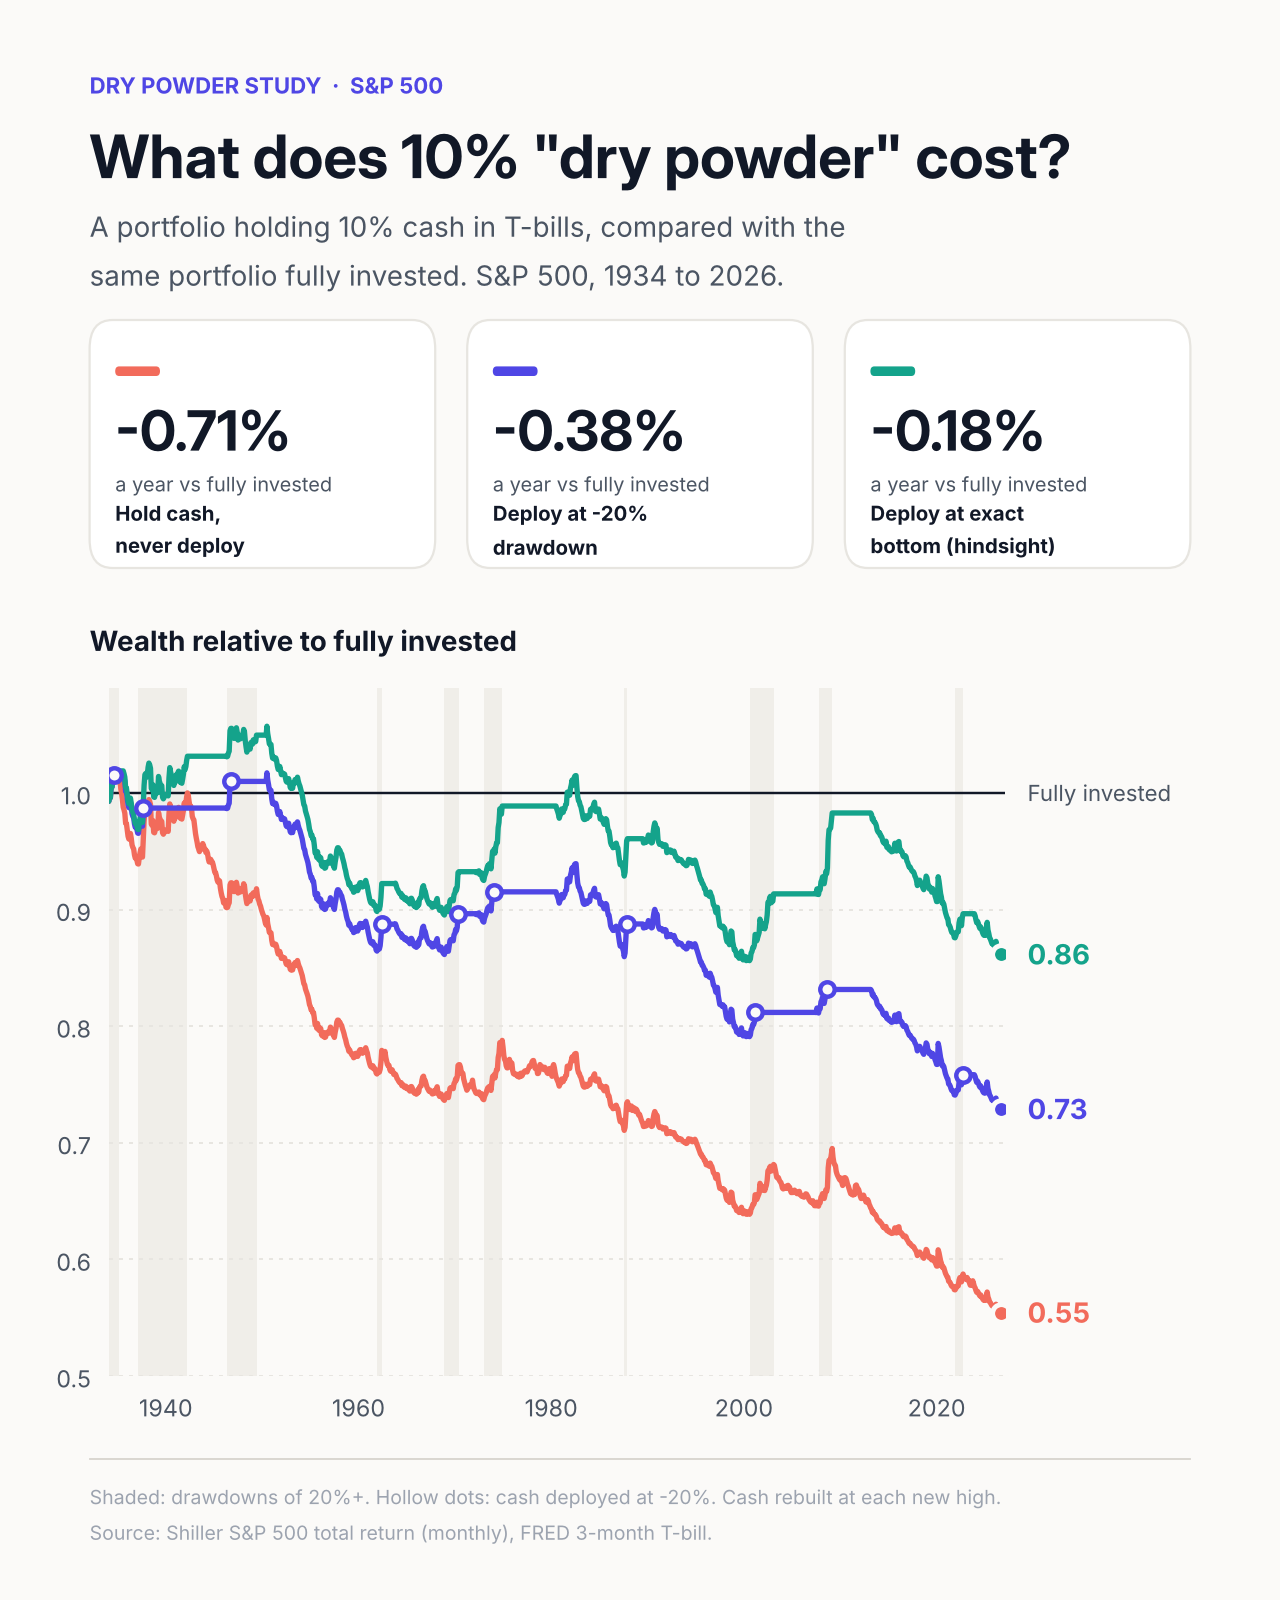
Holding 10% cash and never deploying it returned 0.71 percentage points (pp) a year less than a fully invested portfolio.
Every deployment rule that uses only information available at the time also finished behind, by 0.36 to 0.66 pp a year.
Deploying at the exact bottom of every drawdown of 20% or more, which requires hindsight, still trailed by 0.18 pp a year.
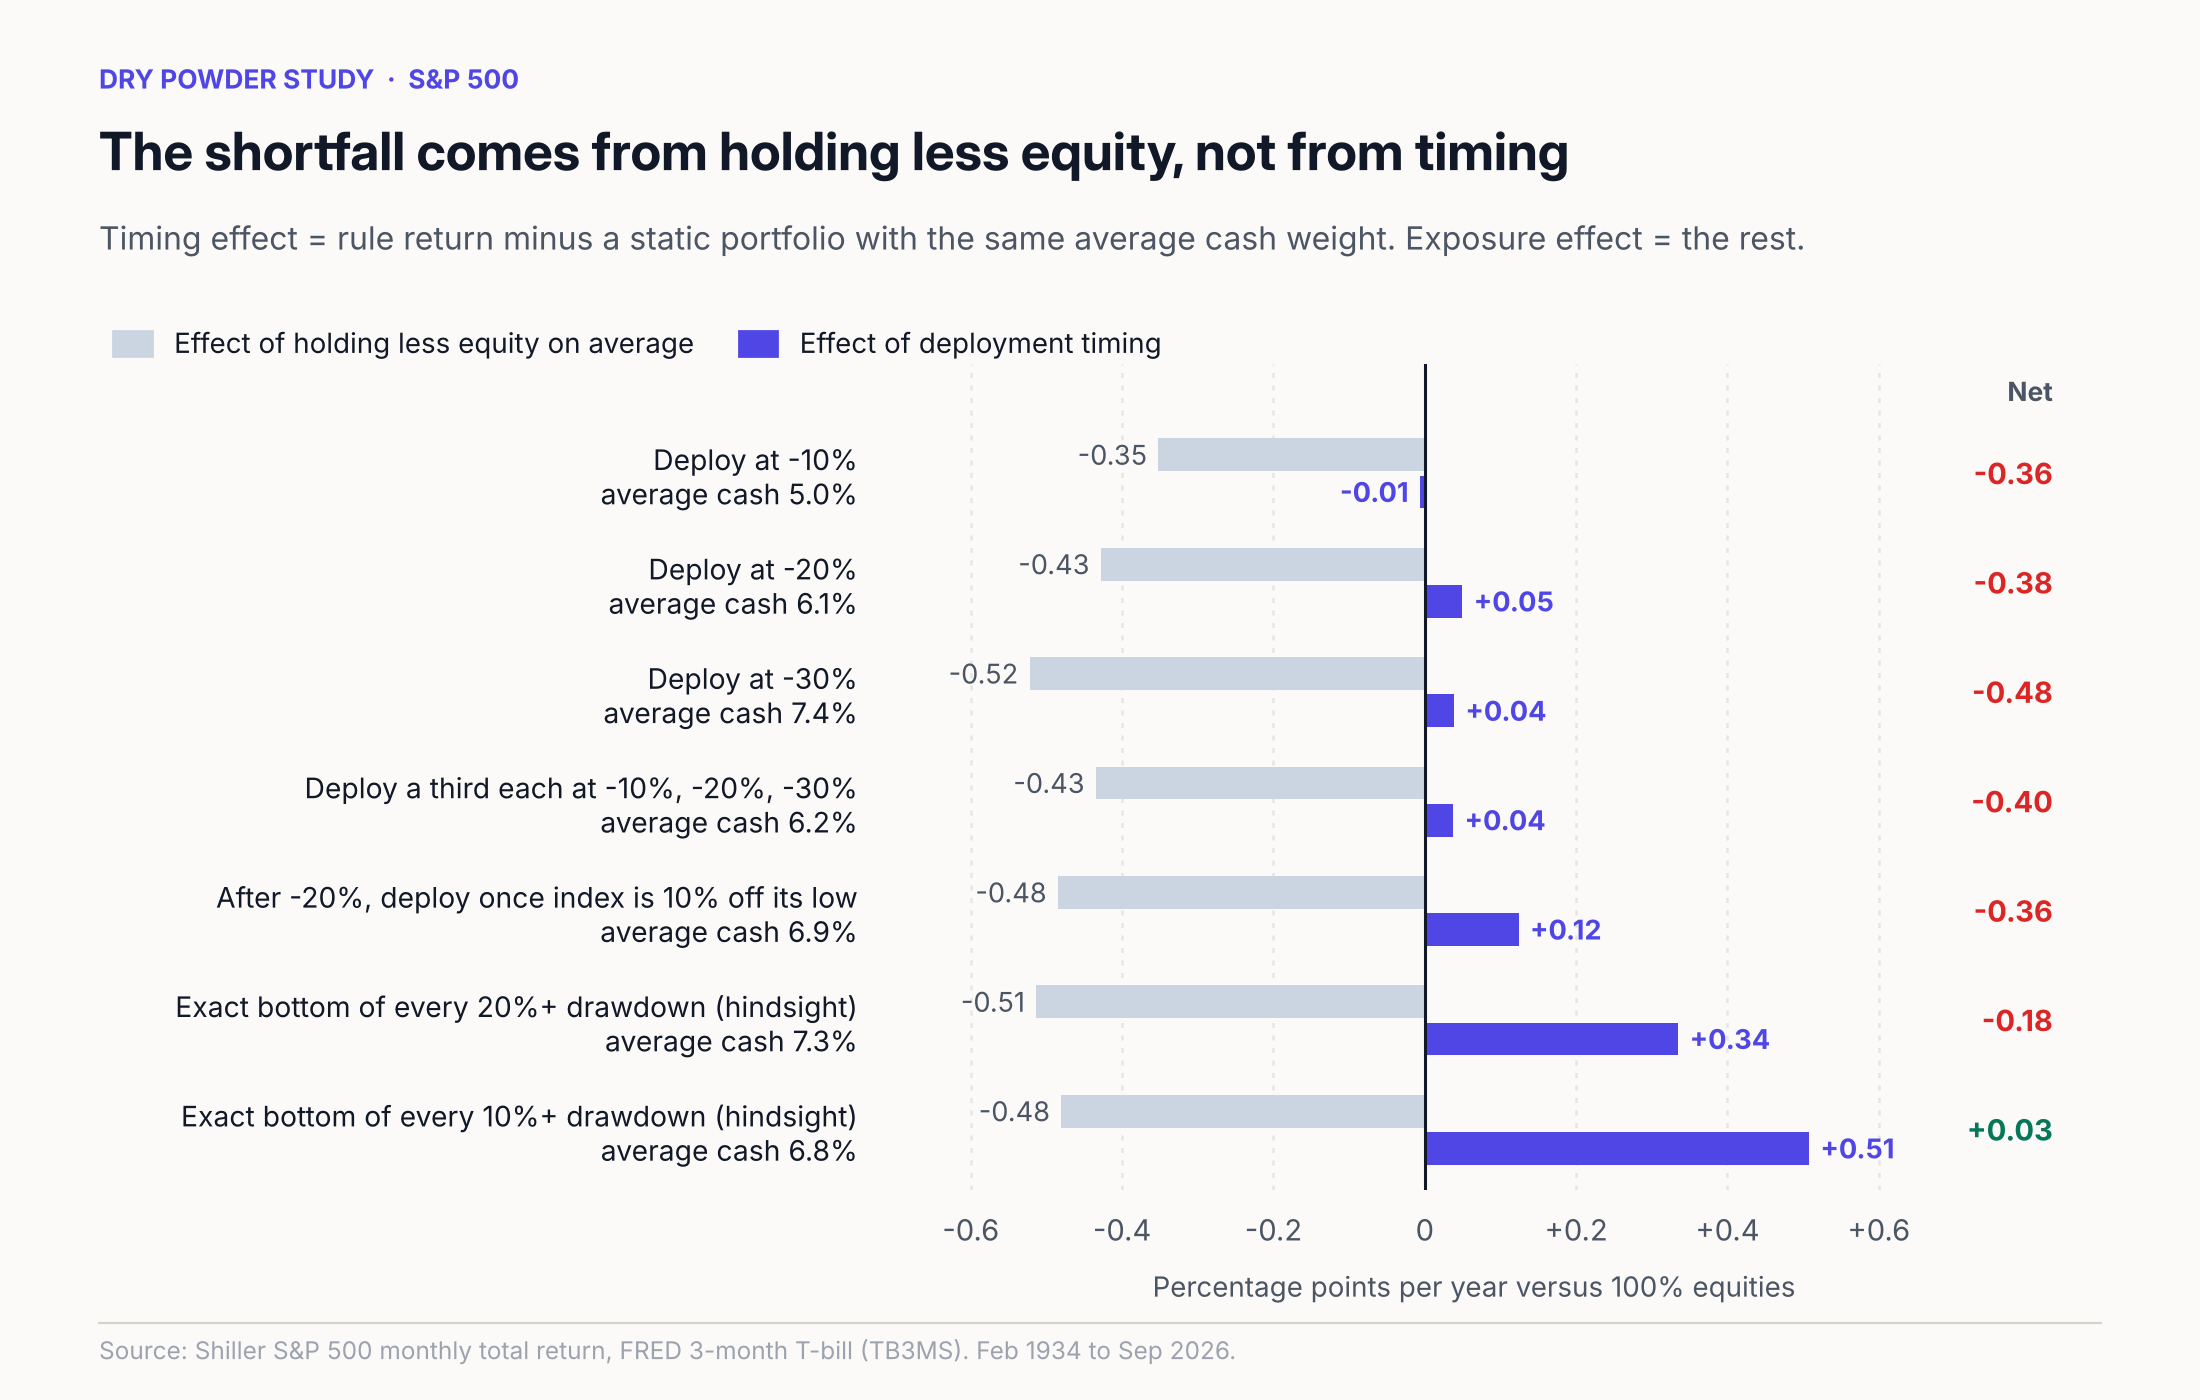
Almost all of the shortfall came from holding less equity on average. Deployment timing added between -0.01 and +0.12 pp a year for rules usable in real time.
Putting the deployed cash into the industries that went on to perform best (perfect foresight) narrowed the gap but did not close it.
The test
The benchmark is 100% S&P 500 with dividends reinvested. The test portfolio holds 90% S&P 500 and 10% cash, rebalanced monthly while it waits. When a deployment rule fires, all of the cash (or a tranche of it) goes into the index. Cash is rebuilt to 10% when the index makes a new all-time high, so each drawdown gets at most one deployment.
Equity data: S&P 500 monthly total return from the Shiller dataset, February 1934 to September 2026.
Cash: earns the 3-month US T-bill rate (FRED series TB3MS). The test starts in 1934 because that is where the T-bill series starts.
Drawdown: the fall in the index from its all-time high.
Timing: decisions use information at the end of a month and take effect the next month. No transaction costs or taxes.
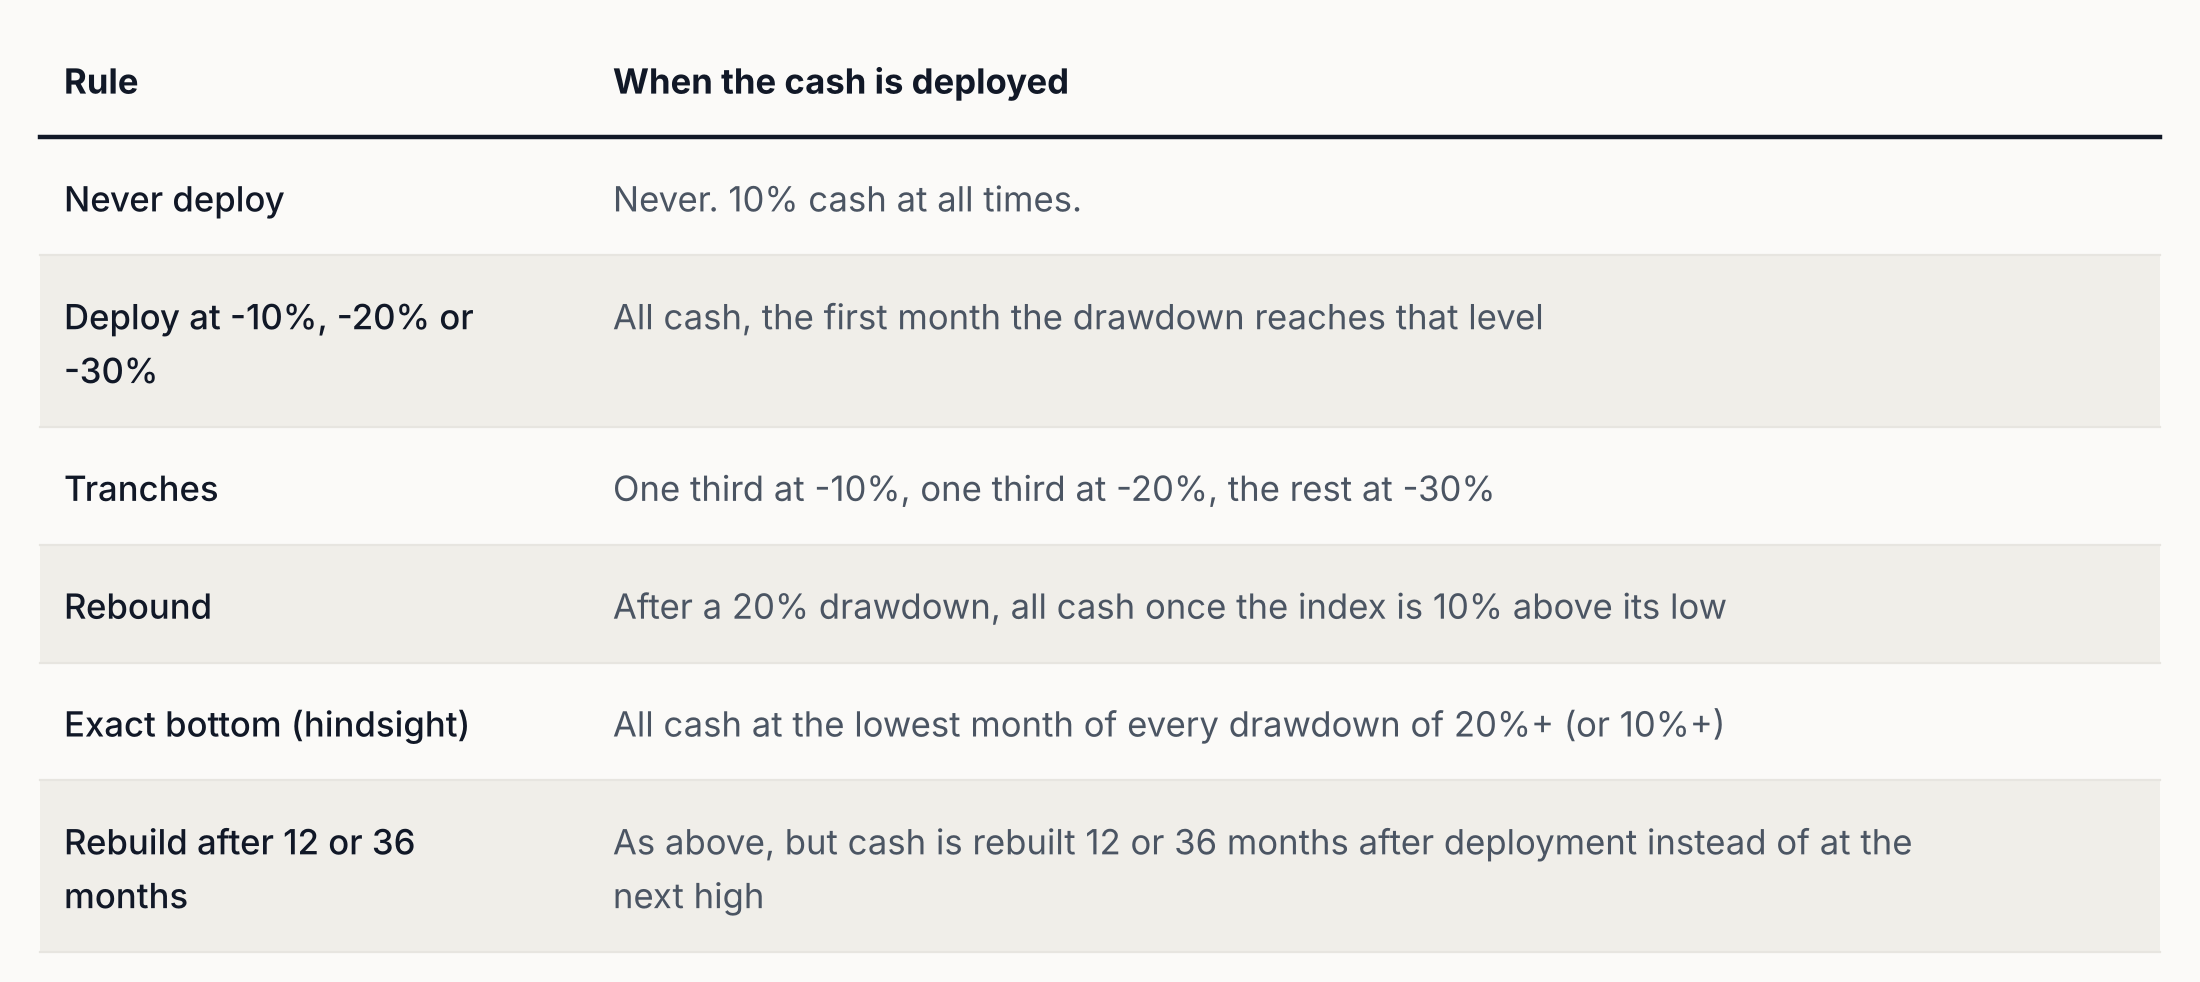
The exact-bottom rules cannot be followed in practice. They set an upper bound on what timing could achieve.
Result 1: every rule finished behind the fully invested portfolio
The fully invested S&P 500 returned 11.13% a year from 1934 to 2026. A portfolio that held 10% cash and never used it ended with 55% of the fully invested portfolio’s wealth. Deploying at a 20% drawdown ended at 73%. Deploying at the exact bottom of every 20%+ drawdown ended at 86%.
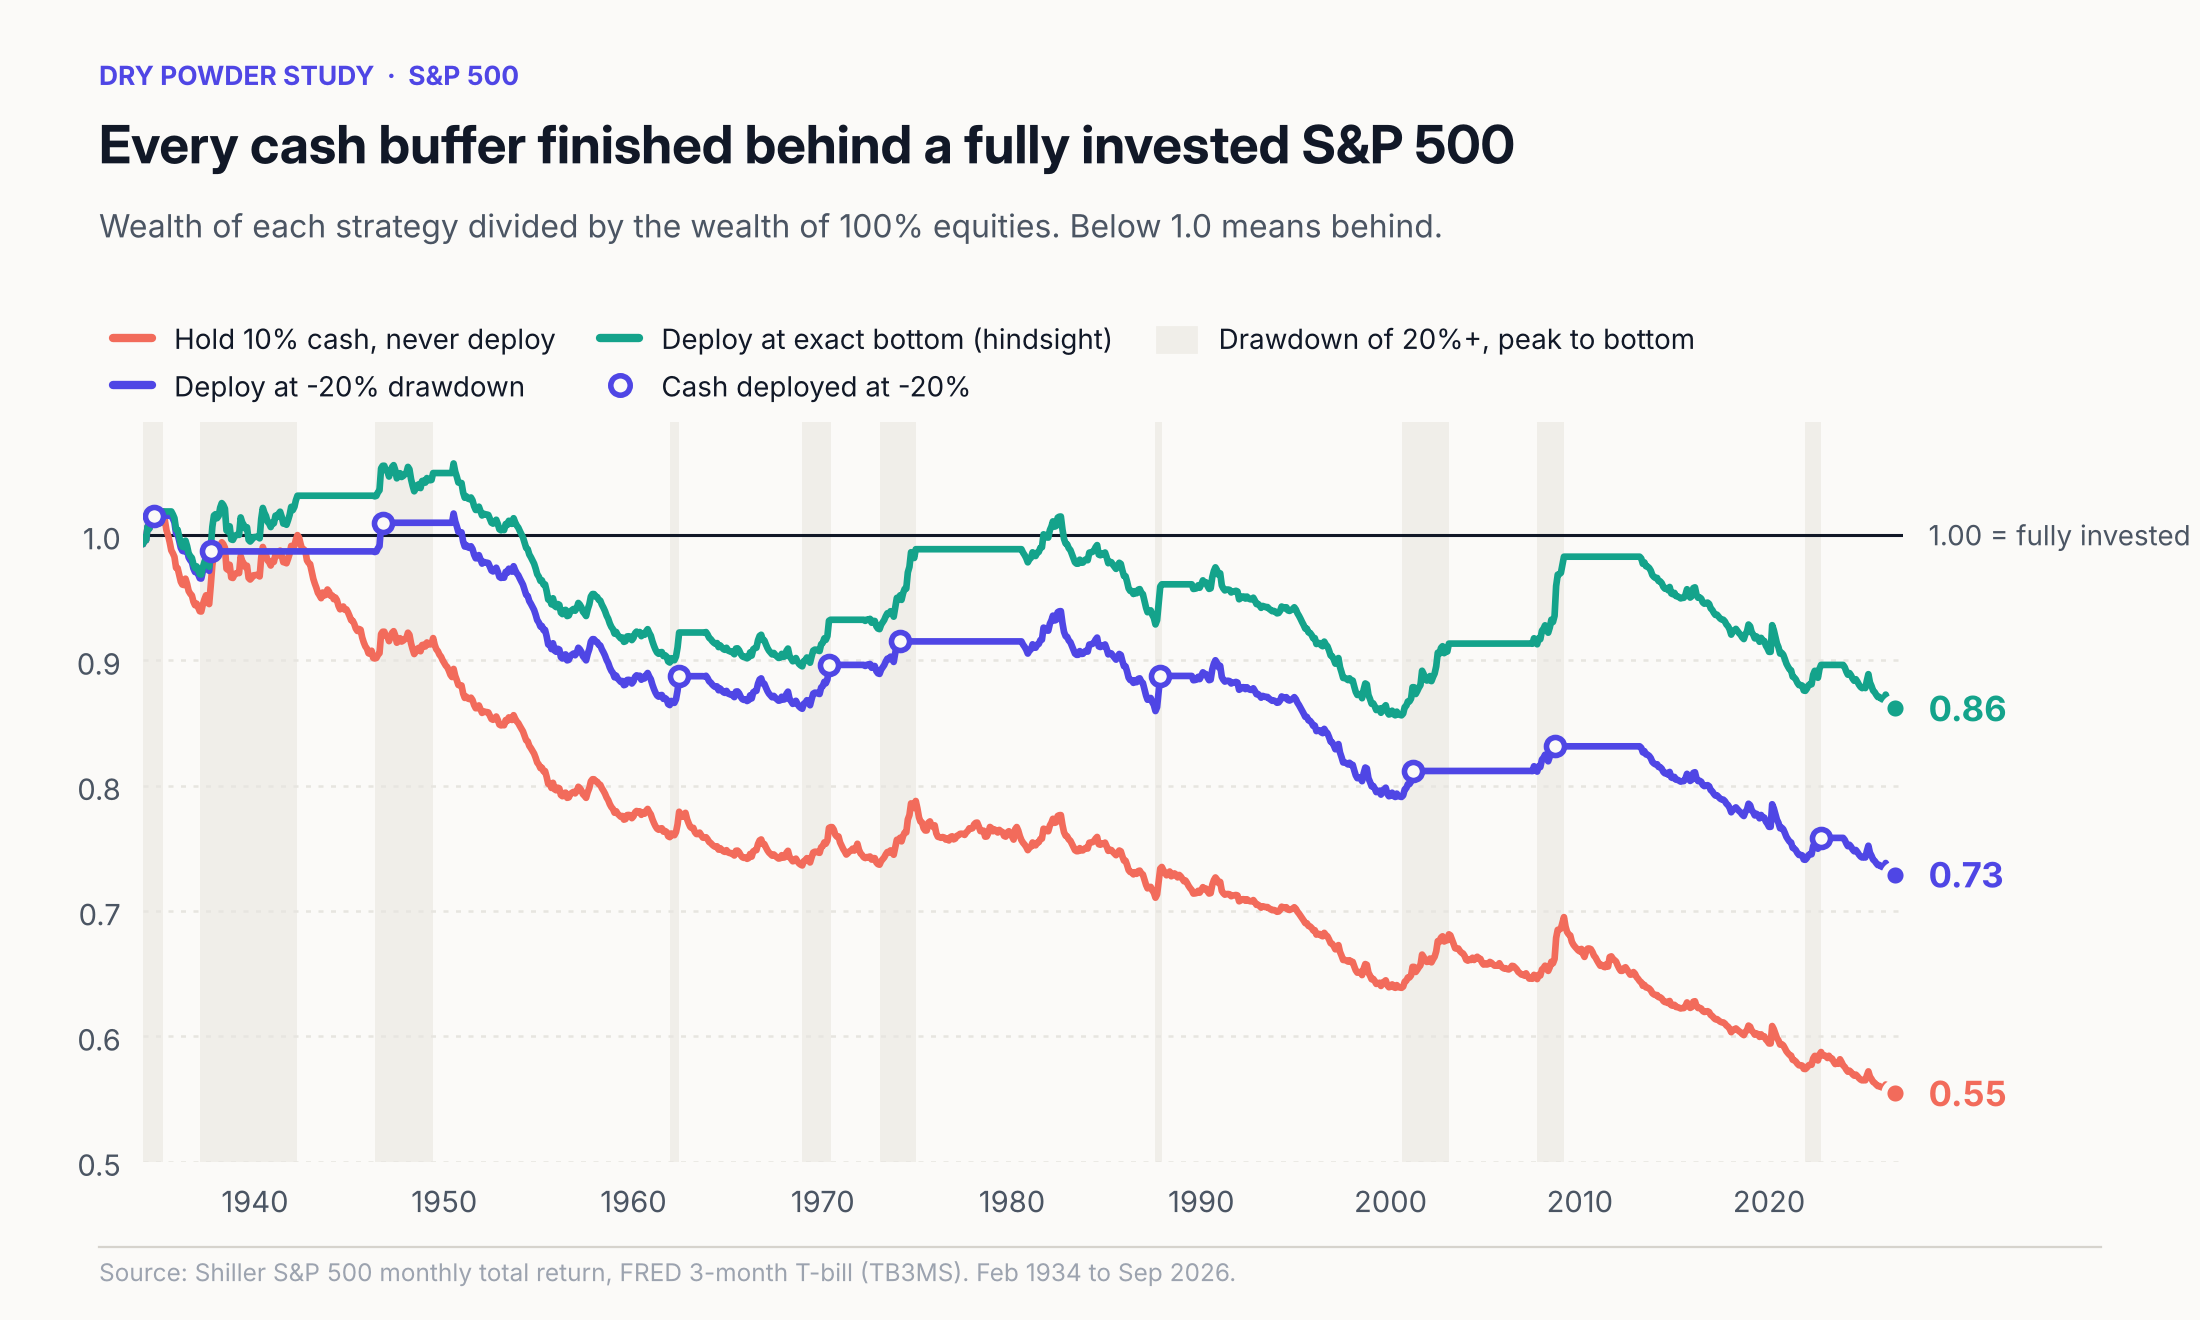
The pattern in the chart repeats in every cycle. The buffer portfolios lose ground slowly during rising markets, then jump when cash is deployed. Over the full period, the jumps did not make up for the ground lost between them.
Two things moved the result more than the trigger level:
How quickly cash was rebuilt. Rebuilding after 12 months cost almost as much as never deploying (-0.65 pp vs -0.71 pp), because the portfolio went back to holding cash while still in a drawdown.
How often cash was deployed. Rules that deployed more often held less cash on average and lost less.
Over rolling 10-year periods, the -20% rule beat the fully invested portfolio in 31% of periods. Holding cash without deploying it beat it in 15%, and only in periods ending between 1974 and 1983 or between 2008 and 2011.
Result 2: the shortfall comes from holding less equity, not from timing
A deployment rule does two things. It lowers the portfolio’s average equity weight, and it moves money into equities at particular times. The two effects can be separated by comparing each rule with a static portfolio that holds the same average cash weight all the time.
The -20% rule held 10% cash in 61% of months and none in the rest, an average of 6.1%. A static portfolio with 6.1% cash returned 10.70% a year. The -20% rule returned 10.75%. Timing added 0.05 pp a year. Holding less equity cost 0.43 pp a year.
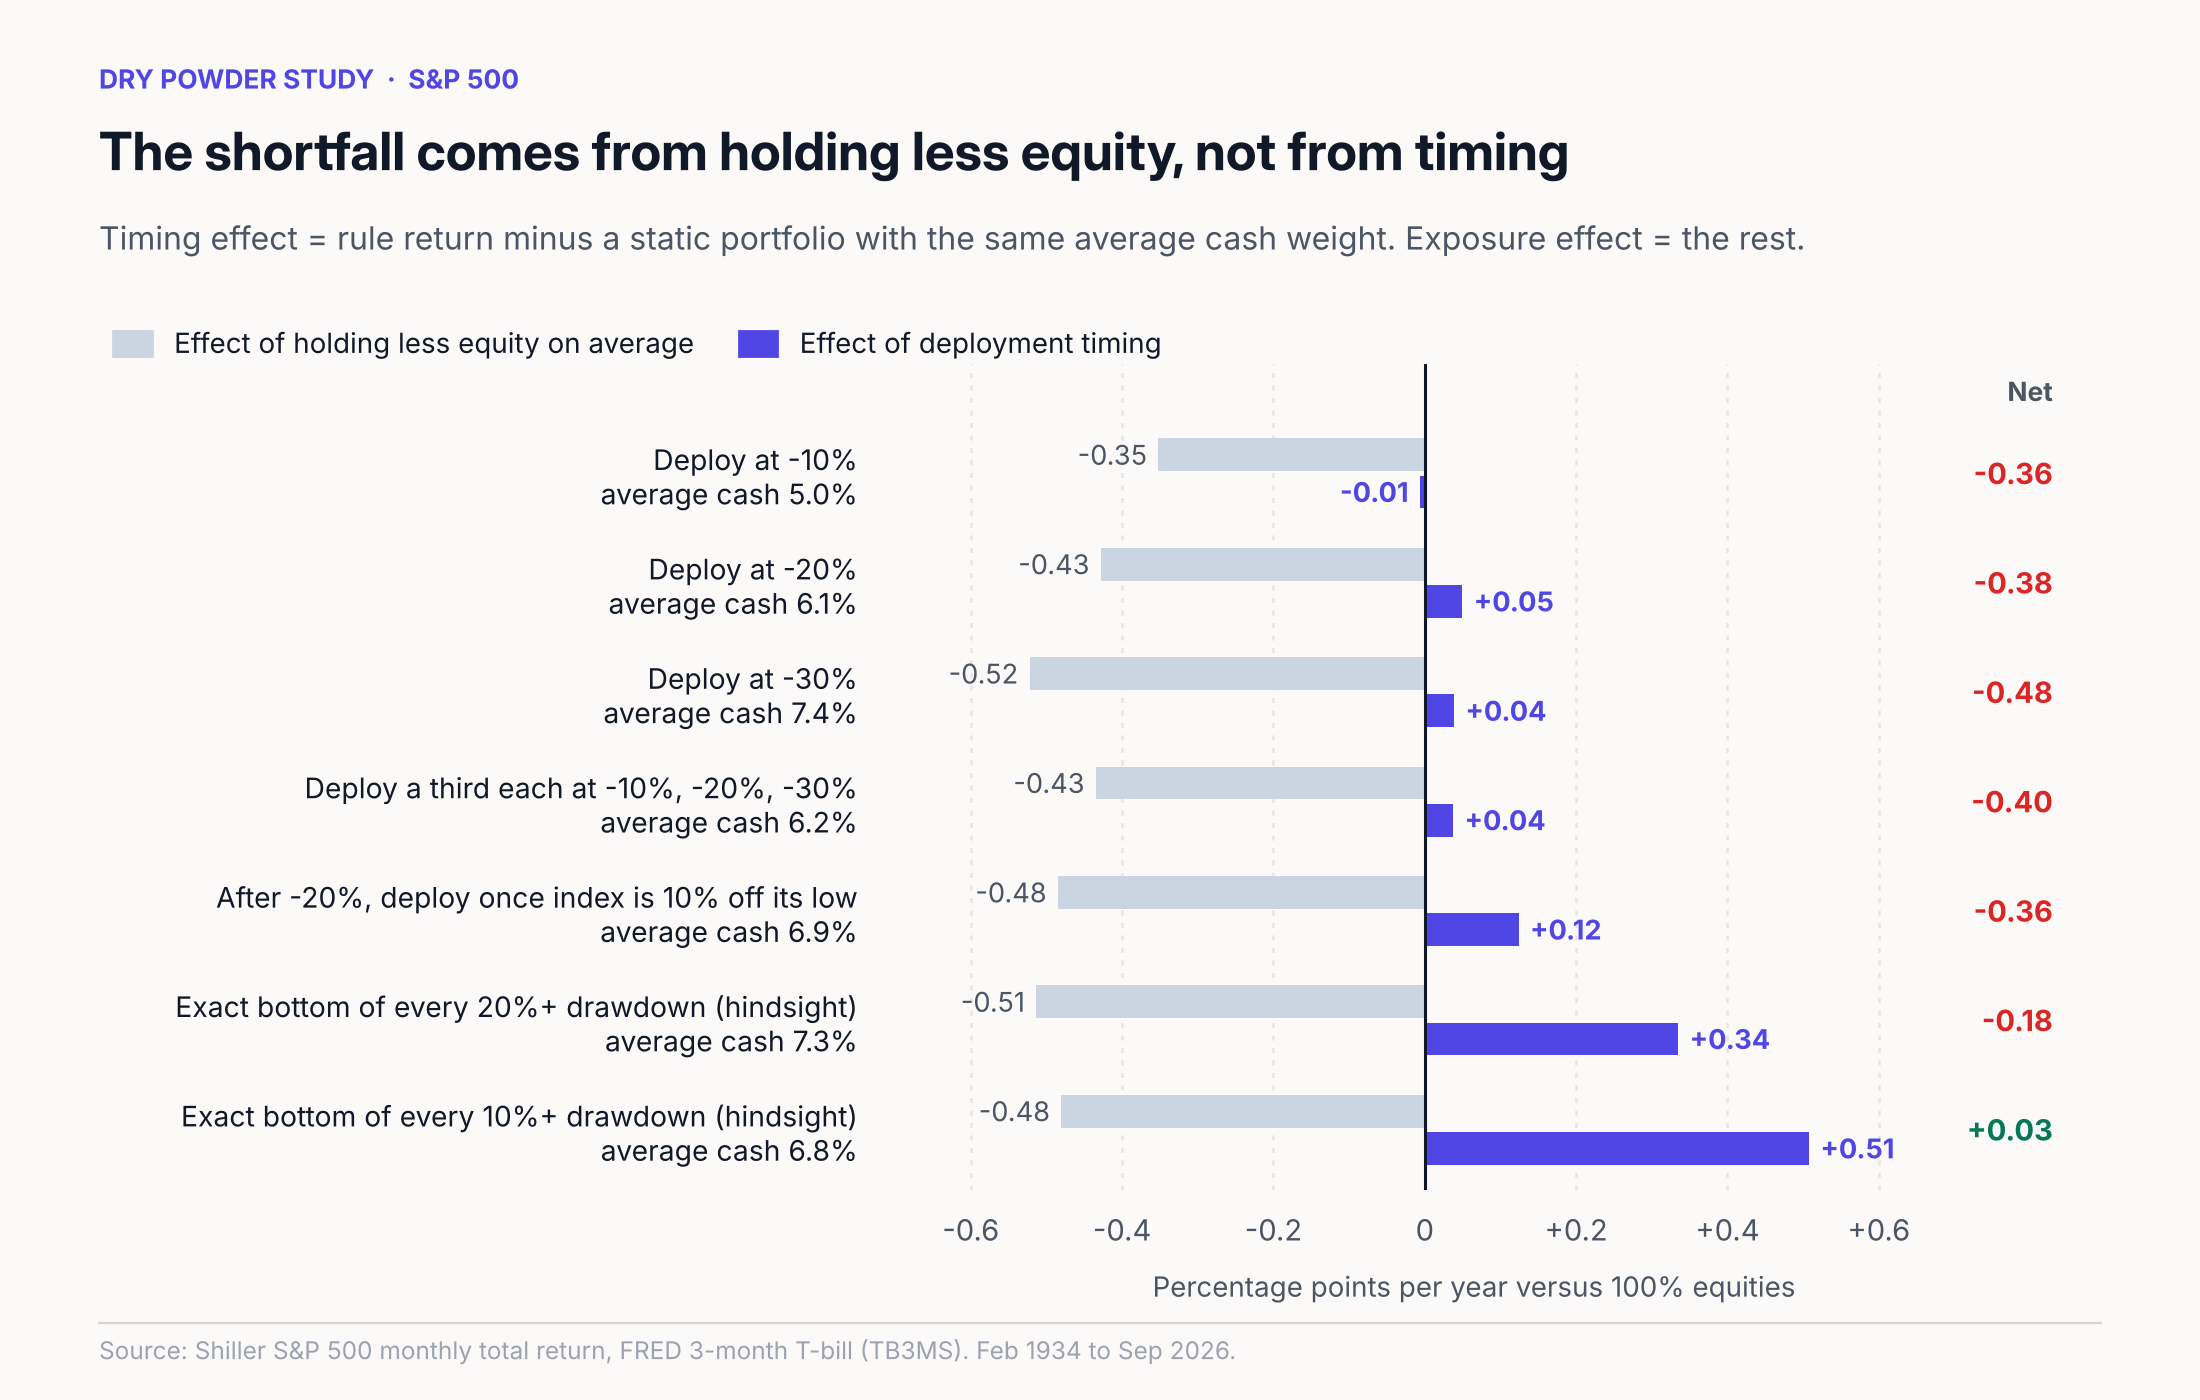
For rules usable in real time, the timing effect ranged from -0.01 to +0.12 pp a year.
With hindsight, deploying at the exact bottom of every 20%+ drawdown added 0.34 pp a year from timing. Its exposure cost was 0.51 pp, so it still finished behind.
The only rule that finished ahead was deploying at the exact bottom of every 10%+ drawdown: 20 perfectly timed deployments in 92 years, for a gain of 0.03 pp a year.
In option terms, the -20% rule paid about 0.43 pp a year for the option and collected about 0.05 pp a year from it.
A 5% cash buffer gives the same result at half the size
Rerunning every rule with 5% cash instead of 10% halves each gap. No rule changes sign.
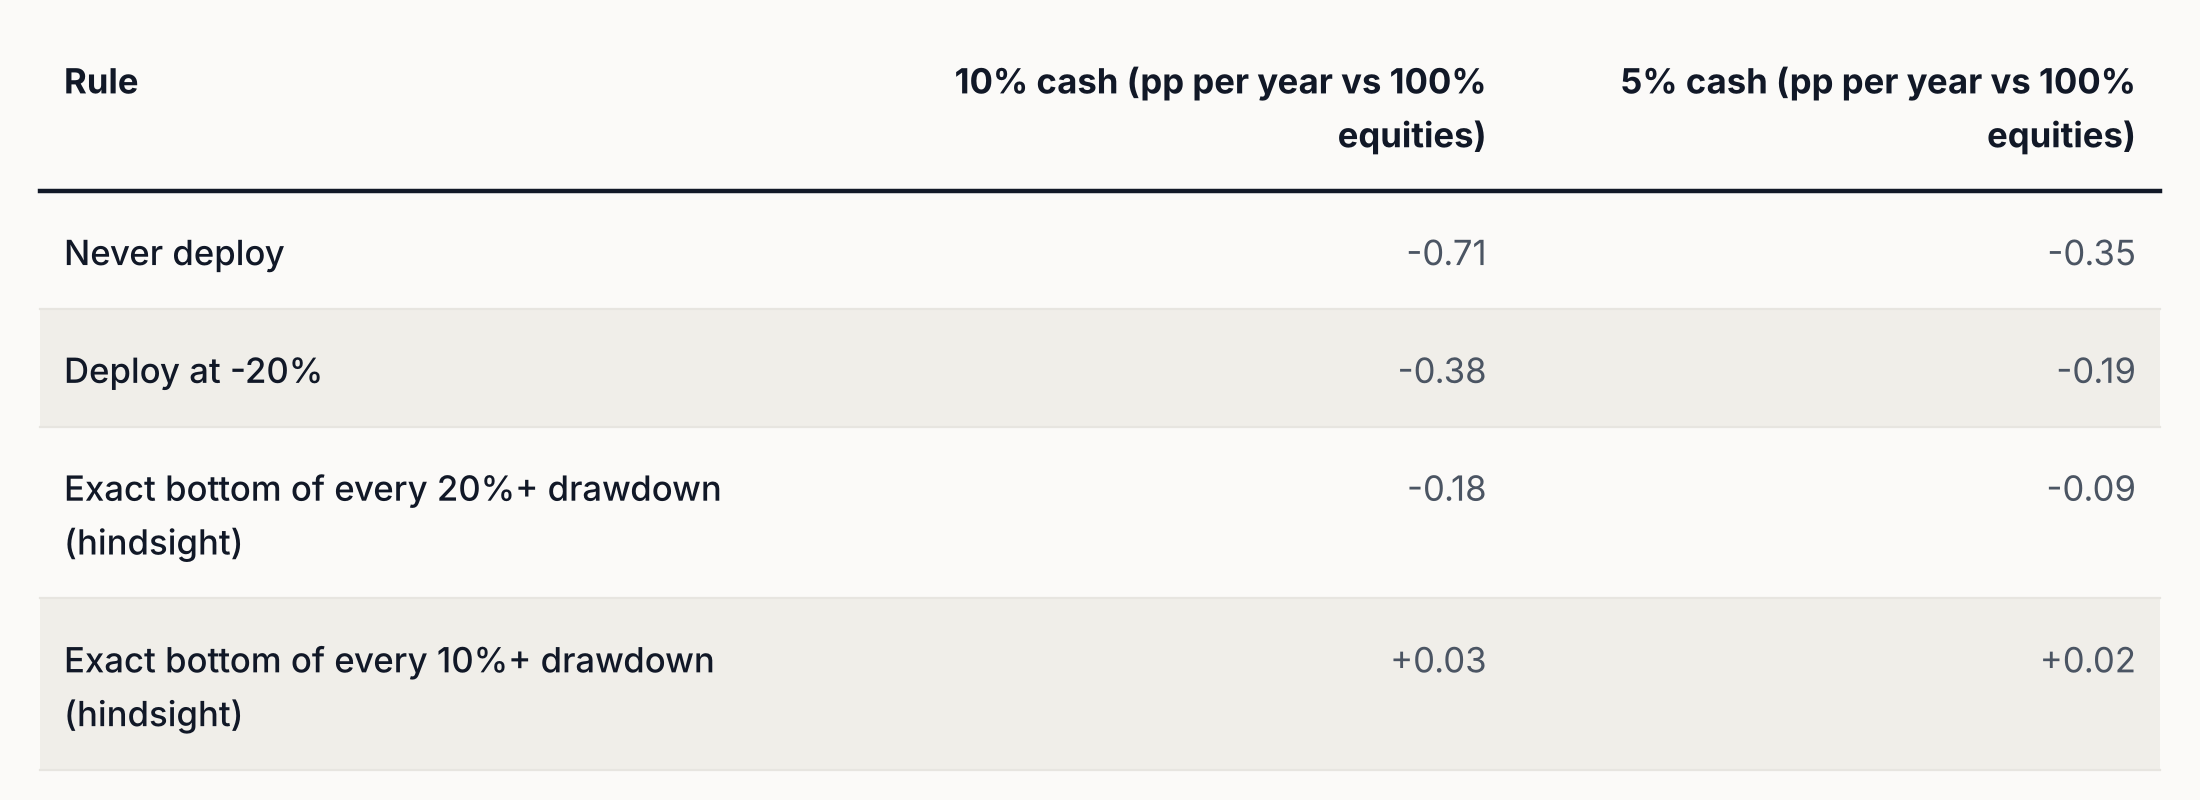
The results scale with the cash weight because both the cost and the payoff are proportional to it. Cash drag is the gap between equity and T-bill returns multiplied by the cash weight. The gain from deploying after a fall is the extra return on the redeployed cash, also multiplied by the cash weight. Halving the cash halves both, so the net result halves and keeps its sign. The timing effect of the -20% rule falls from +0.05 to +0.025 pp a year for the same reason.
A smaller buffer costs less each year. Every rule that can be followed in real time still finishes behind the fully invested portfolio.
Result 3: the drawdowns paid, the waiting did not
The sample has nine drawdowns of 20% or more with enough history before them to test. For each one, the cash buffer’s result depends on two numbers: how long the cash was held before it was deployed, and how much cheaper the index was when it went in.
Once the cash is deployed, both portfolios are fully invested and move together. Measuring 12 months after deployment, or any other period, gives the same relative result as measuring on the deployment date. The whole outcome is fixed when the cash goes in.
If cash is held for only the 12 months before the market peak, the buffer did well. Deploying at -20% beat full investment in 6 of 9 drawdowns. Deploying at the exact bottom beat it in 7 of 9, by up to 6.7% of portfolio value (2007 to 2009).
Under the actual rule, cash was not held for 12 months. It was rebuilt at each new market high and then held until the next 20% drawdown, which took between 6 and 144 months (median 80). The longest holding period that still broke even had a median of 36 months.
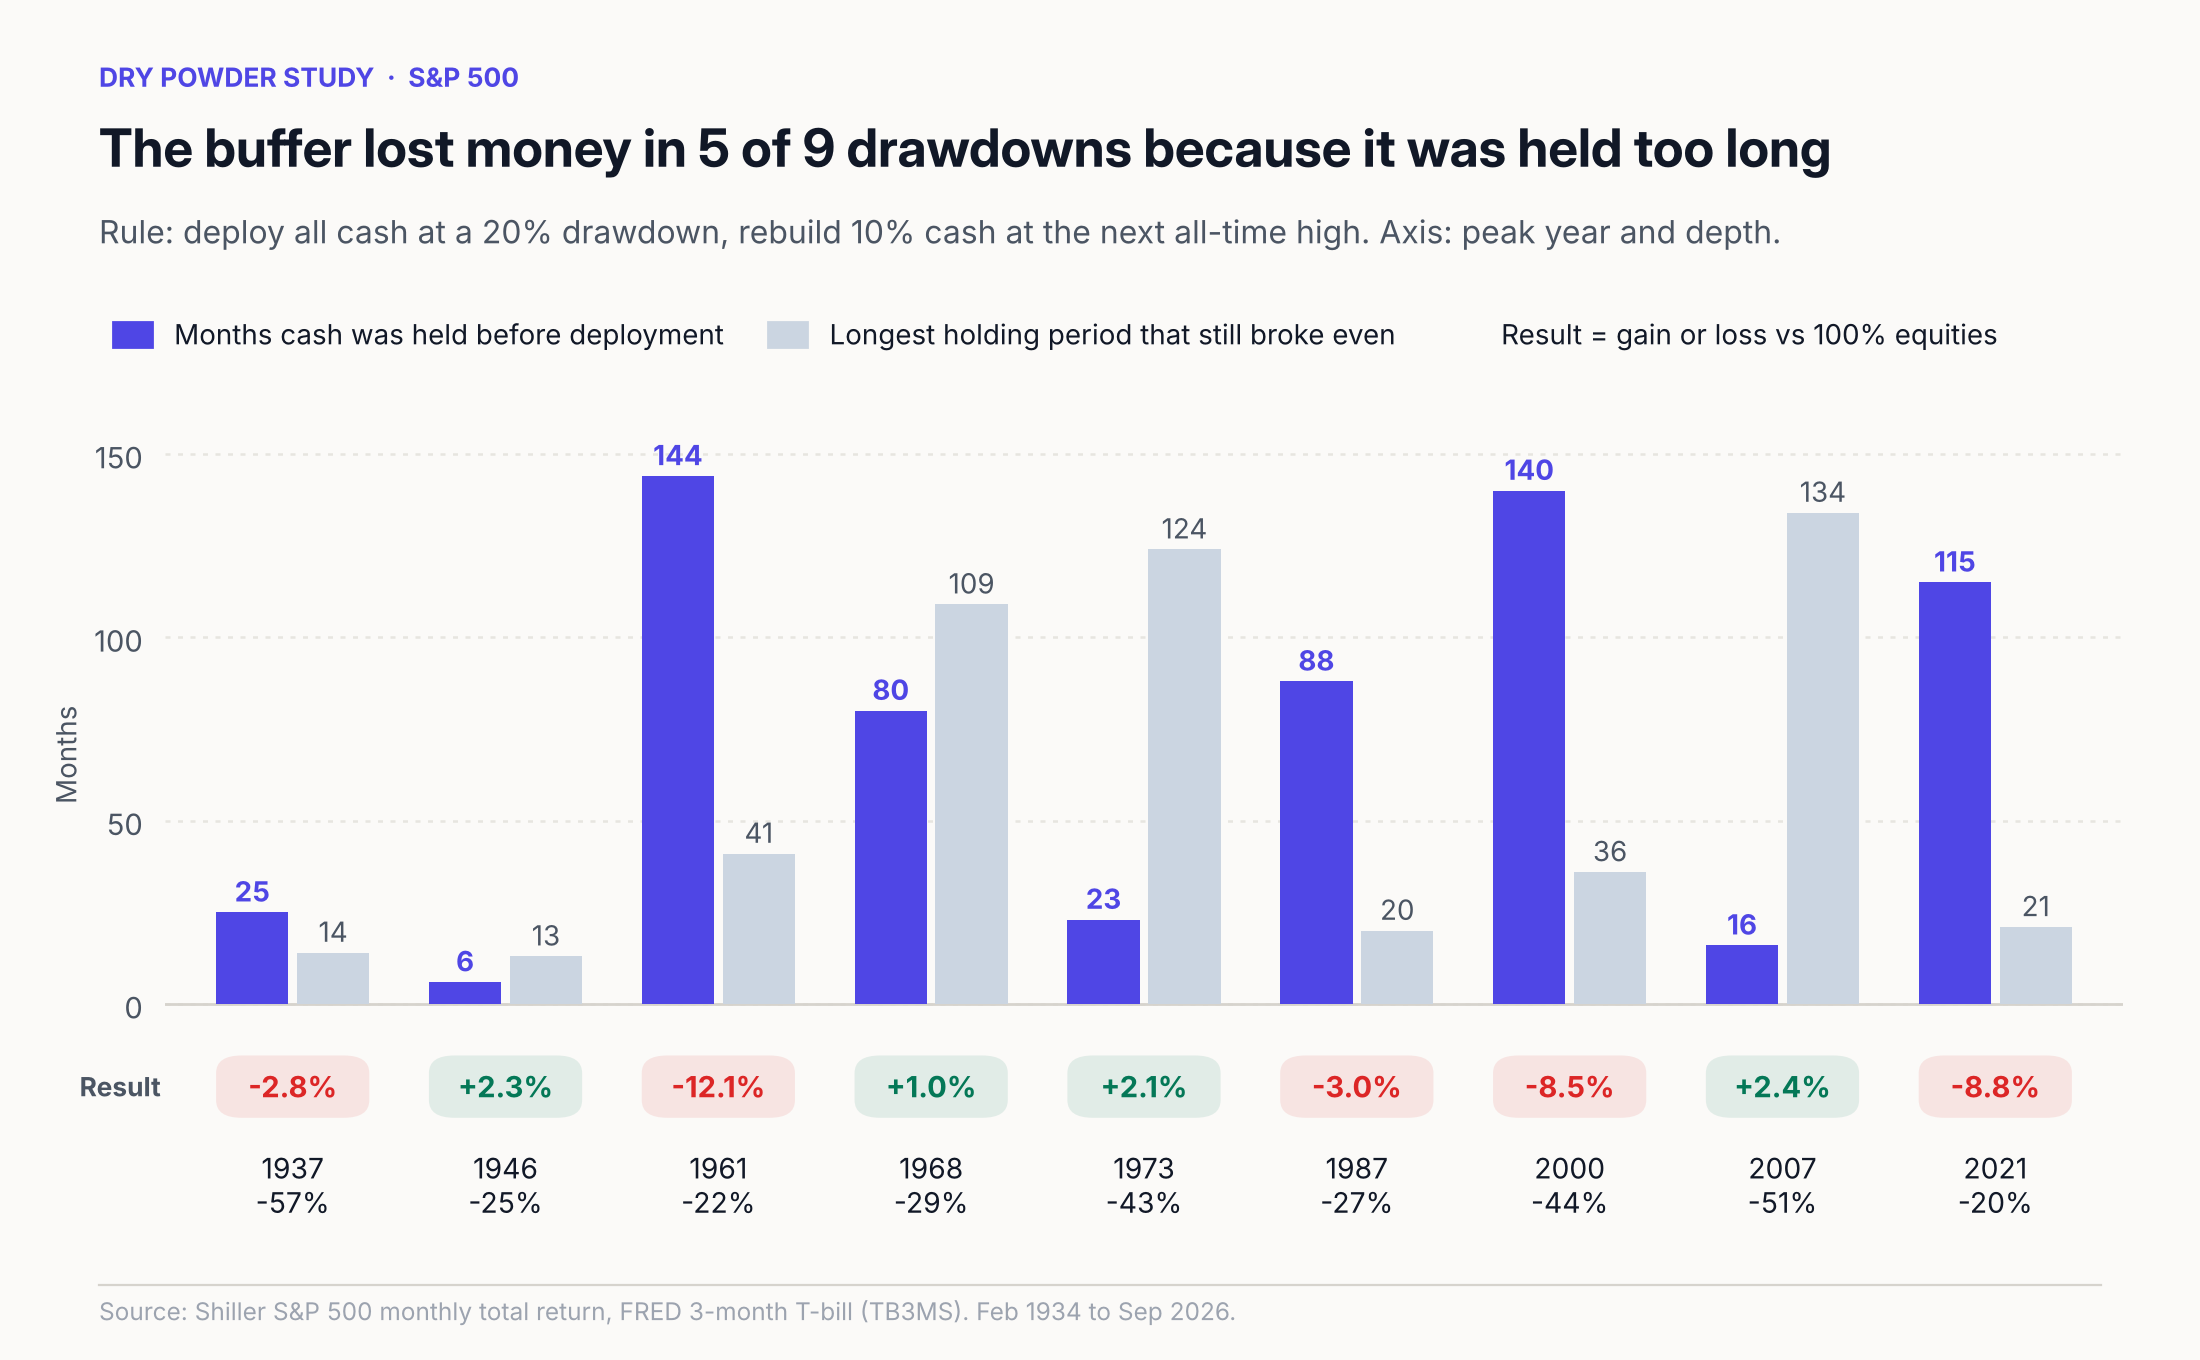
The buffer lost money in the 5 drawdowns where it was held longer than the breakeven period.
Gains in the other 4 were between 1.0% and 2.4% of portfolio value. Losses were between 2.8% and 12.1%.
The two largest gains (1946 and 2008) followed waits of 6 and 16 months. The largest loss (1962) followed a wait of 144 months.
A manager holding cash for a drawdown does not know when the peak will come. The cost of holding cash accumulates for every month of waiting, and the waiting periods in this sample were long.
Result 4: stock picking with the deployed cash
A manager might argue that the cash is not meant to buy the index. It is meant to buy the best opportunities a selloff creates. To test this, the deployed cash goes into a basket chosen with perfect foresight of the next 12 months.
Stock-level data with historical index membership was not available for this test, so it uses industries instead. The data is the Ken French 12-industry US portfolios and the CRSP value-weighted market, monthly, January 1949 to March 2017. At each deployment, the 12 industries are ranked by their return over the next 12 months. The cash goes into the top, 2nd, 3rd or bottom quartile (3 industries each, equal weight) for 12 months, then into the market.
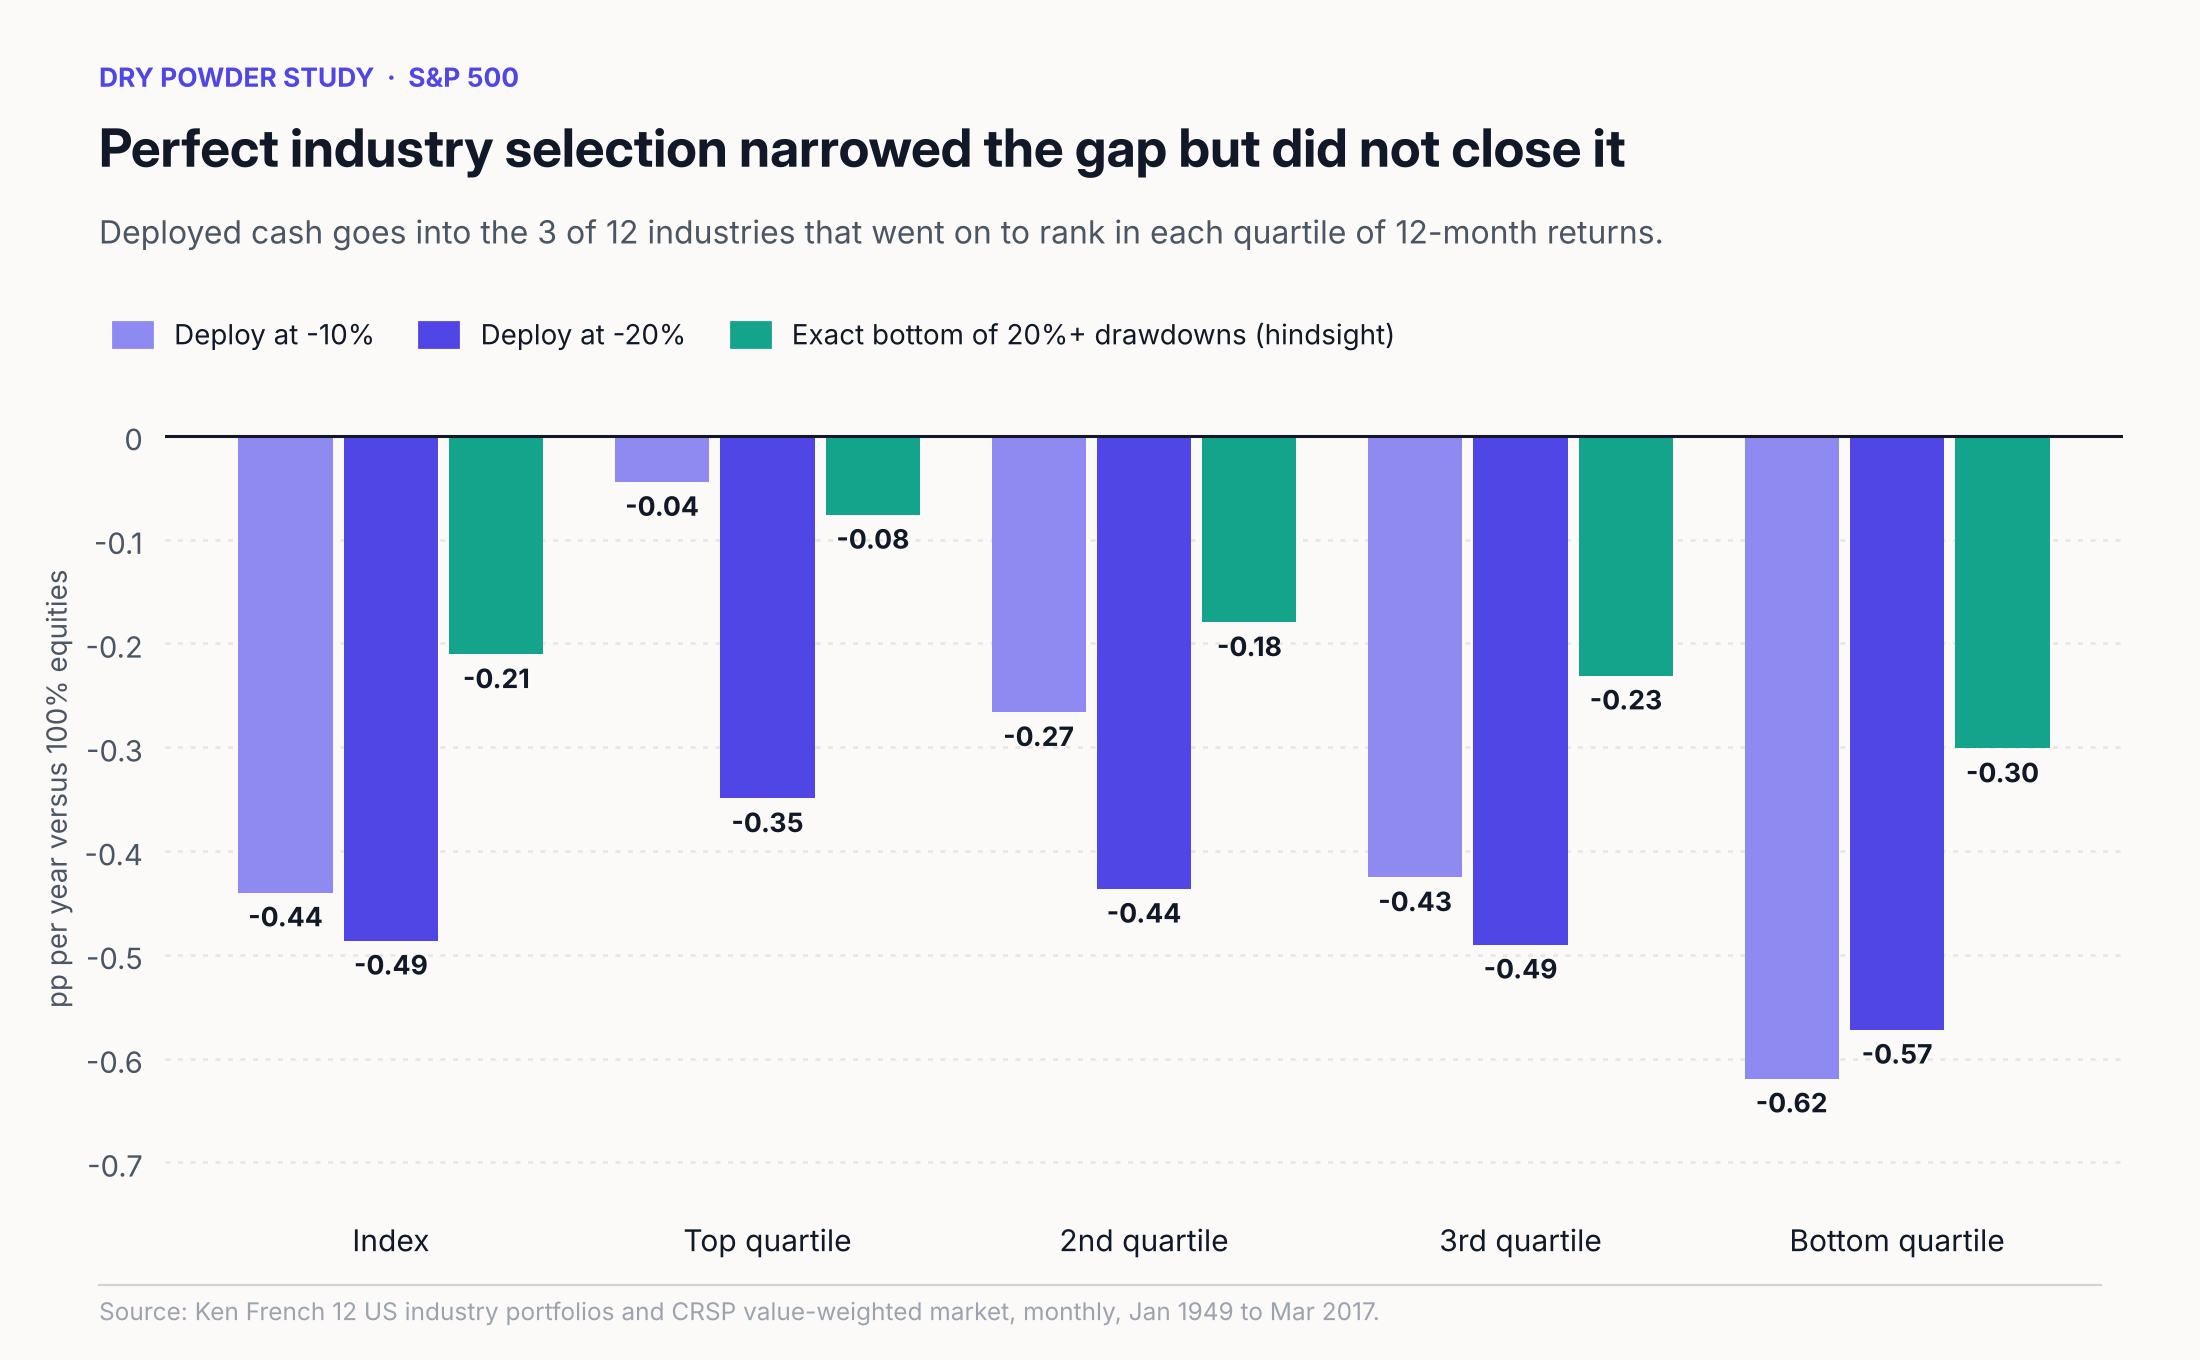
Buying the top-quartile industries at -20% improved the result from -0.49 pp to -0.35 pp a year. It did not close the gap.
The best combination tested, deploying at every -10% drawdown into the top-quartile industries, finished at -0.04 pp a year.
Buying the bottom quartile made every rule worse, by 0.08 to 0.18 pp a year.
Over the six -20% deployments, the top-quartile industries beat the market by 8 to 16 pp over the following 12 months. On 10% of the portfolio, that is 0.8% to 1.6% of portfolio value per deployment, against cash drag paid in every year between deployments.
Industry baskets are less dispersed than individual stocks, so a stock picker with genuine foresight could add more than this. But a manager with that skill can apply it to the other 90% of the portfolio as well. The skill is an argument for active management, not for holding cash.
Pricing the option
The cost of 10% cash is roughly 10% of the equity risk premium over T-bills. In this sample that was 0.71 pp a year while the cash was held. A rule that deploys and rebuilds pays less, because it holds cash only part of the time: the -20% rule paid about 0.43 pp a year.
To break even, the timing of deployments has to earn back that cost. In this sample, real-time rules earned back between nothing and a quarter of it. Only perfect hindsight on every 10% drawdown earned it all back.
There is a listed instrument that does what the cash buffer is meant to do: a put option written against cash. The put writer agrees to buy the index if it falls below the strike price, keeps the cash in T-bills until then, and is paid a premium for the commitment. The cash-buffer manager pays for the same intention through cash drag and is paid nothing.
The Cboe S&P 500 PutWrite Index (PUT) tracks this strategy, writing one-month at-the-money puts against T-bills. A Cboe-sponsored study by Oleg Bondarenko found that from mid-1986 to 2015, PUT returned 10.13% a year against 9.85% for the S&P 500, with a standard deviation of 10.16% against 15.26%. Put writing was not tested in this backtest; those figures are from the study.
Questions to ask a manager who holds cash for optionality
What has the average cash weight been over a full cycle, not just today?
What decides when the cash is deployed? Is there a rule, and what drawdown level does it use?
When is the cash rebuilt?
What has the cash position contributed to returns, measured against a fully invested version of the same portfolio?
Over how many years was the drag paid for each deployment that added value?
Limitations
Monthly average prices. The Shiller series uses monthly averages of daily closes, so drawdowns look shallower than on daily data. In 2020 the S&P 500 fell about 34% on daily closes but 19.1% on monthly averages, so the -20% rule did not trigger. The -10% rule did.
Robustness check. The same rules on month-end CRSP market returns (Ken French data, 1949 to 2017) gave the same ranking: never deploy -0.62 pp a year, deploy at -20% -0.49 pp, exact bottom of 20%+ drawdowns -0.21 pp.
Dividends after June 2023 are not in the dataset and were filled at a 1.3% annual yield.
Risk. Every buffer portfolio had lower volatility than the fully invested one (11.5% to 12.3% against 12.8%), as any portfolio with less equity would. The comparison here is on return.
Scope. US market only. No transaction costs or taxes. Industries, not stocks, in the stock-picking test.
Sources
Shiller S&P 500 monthly data, via the datasets/s-and-p-500 repository
Kenneth R. French Data Library (12-industry portfolios and market returns, as bundled in the linearmodels Python package)
Cboe: New study on weekly and monthly S&P 500 PutWrite indexes (2016)
Informational only, not advice.
Finding that even a perfect-hindsight deployment at every 20%+ drawdown still trailed a fully invested portfolio by 0.18 points a year makes the cash-drag cost clear. Most of the gap coming from lower average equity exposure rather than timing is the key point.